Key points
- The controversy centers on Royal Orchid Hotels (Thailand) Public Company Limited (ROH) and the Grand Royal Orchid Hospitality Real Estate Investment Trust (GROREIT), following ROH’s failure to complete a contractual asset repurchase originally scheduled for July 14, 2026.
- As this Thailand Hotel News report examines, the continuing legal proceedings have left unit holders facing mounting financial exposure despite having originally invested in a structure designed to support the hotel during the COVID-19 pandemic.
- The situation became particularly frustrating for unit holders after they approved an alternative asset sale to a major investor for approximately 5.
A prolonged financial and legal dispute involving Bangkok’s iconic Royal Orchid Sheraton hotel is raising serious questions about investor protection, contractual obligations, and the reliability of Thailand’s real estate investment trust (REIT) market. With millions of baht potentially being lost through delays and a major bank repayment deadline approaching, investors are increasingly concerned about the consequences of the unresolved dispute.
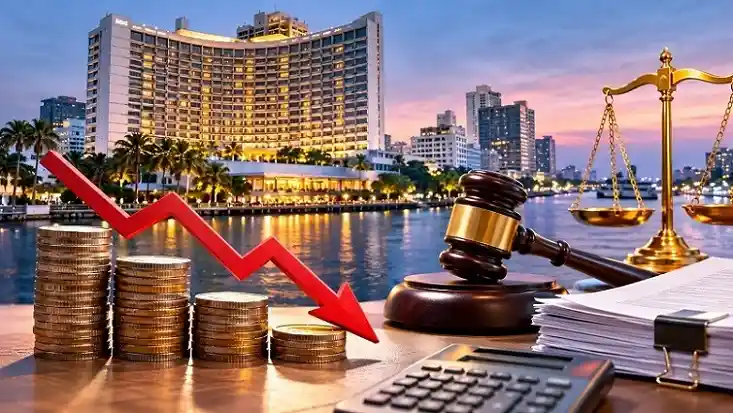
Image Credit: Thailand Hotel News
The controversy centers on Royal Orchid Hotels (Thailand) Public Company Limited (ROH) and the Grand Royal Orchid Hospitality Real Estate Investment Trust (GROREIT), following ROH’s failure to complete a contractual asset repurchase originally scheduled for July 14, 2026. As this Thailand Hotel News report examines, the continuing legal proceedings have left unit holders facing mounting financial exposure despite having originally invested in a structure designed to support the hotel during the COVID-19 pandemic.
A Financial Lifeline That Has Become an Investor Nightmare
GROREIT was established during the pandemic as a financing mechanism intended to provide much-needed liquidity for the Royal Orchid Sheraton hotel business when Thailand’s hospitality industry was experiencing unprecedented difficulties.
Investors were attracted partly by an arrangement requiring the repurchase of assets after five years. This contractual commitment provided reassurance that their investment would eventually be recovered through a predetermined transaction.
However, when the July 2026 deadline arrived, ROH did not complete the agreed repurchase, triggering a dispute that has continued through subsequent legal proceedings.
The situation became particularly frustrating for unit holders after they approved an alternative asset sale to a major investor for approximately 5.3 billion baht, only for the transaction to remain unresolved.
Court Extension Adds Another Layer of Uncertainty
The latest development involves ROH’s request for additional time to deposit security amounting to approximately 4.873 billion baht.
Although ROH reportedly requested a one-month extension beyond the court’s original seven-day period, the court granted only another seven days, establishing November 24, 2026, as the revised deadline.
For investors, this extension represents another period of uncertainty rather than a definitive resolution.
Each additional delay potentially increases financing expenses while postponing the distribution of proceeds that unit holders anticipated receiving following the asset sale.
The dispute also highlights the difficulties investors can encounter when contractual repurchase arrangements become entangled in litigation.
Financial Exposure Exceeds 274,000 Baht Every Day
According to financial estimates presented by concerned unit holders, the continuing delays generate approximately 274,110 baht in daily financing expenses and foregone investment returns.
The largest component involves GROREIT’s outstanding 1.35 billion baht loan from the Government Savings Bank.
Based on an interest rate estimated at approximately MLR minus 1.6 percentage points, financing expenses amount to roughly 170,000 baht daily, equivalent to approximately 5.1 million baht monthly or 62.05 million baht annually.
These obligations continue accumulating while the asset transaction remains incomplete.
A second component involves the estimated opportunity cost associated with approximately 3.8 billion baht in potential net proceeds after repayment of bank borrowings and transaction-related expenses.
Assuming those proceeds could generate a modest annual return of 1%, unit holders would potentially forgo approximately 104,110 baht daily, equivalent to 38 million baht annually.
Combined, these estimates suggest that a seven-day delay represents approximately 1.92 million baht in economic costs, while a 30-day delay could exceed 8.22 million baht.
Importantly, the opportunity-cost component represents hypothetical foregone earnings rather than an actual cash payment.
January 2027 Loan Deadline Creates Additional Pressure
Beyond the immediate financial implications, GROREIT faces another significant challenge involving its outstanding Government Savings Bank borrowing.
The 1.35 billion baht loan reportedly becomes due on January 15, 2027, creating a potentially serious liquidity problem if the asset transfer remains incomplete.
Without sufficient proceeds from the transaction, the trust could encounter repayment difficulties unless alternative financing arrangements or an extension are negotiated.
Any default or additional penalty interest could further diminish the amount ultimately available for distribution to unit holders.
The approaching deadline therefore makes the timely resolution of the dispute increasingly important.
Wider Implications for Thailand’s REIT Market
The Royal Orchid Sheraton dispute extends beyond the financial interests of one hotel investment vehicle.
REITs depend heavily on investor confidence in contractual protections, transparent governance, predictable cash flows, and enforceable transaction agreements.
When an anticipated asset repurchase becomes prolonged litigation, investors may reassess the risks associated with similar financing structures.
Such concerns could eventually affect fundraising costs and investor appetite for hospitality-related trusts, particularly those incorporating future repurchase commitments.
Nevertheless, the circumstances surrounding GROREIT should not automatically be interpreted as evidence of systemic weaknesses across Thailand’s entire REIT industry.
A Critical Test of Investor Protection
The coming weeks could prove decisive for GROREIT and its investors. With the November 24 security deadline approaching and a substantial bank repayment obligation looming in January, resolving the transaction has become increasingly urgent. Beyond the immediate financial consequences, the dispute underscores why enforceable agreements, effective governance, and timely dispute resolution remain essential to maintaining confidence in Thailand’s hospitality investment market.