Key points
- The riverside property is among Bangkok’s best-known large hotels, and the proposed transaction has placed its future in the hands of unitholders of the Grande Royal Orchid Hospitality Real Estate Investment Trust with Buy-Back Condition, or GROREIT.
- At the center of this Thailand Hotel News report is a wider question over how GROREIT should dispose of its principal assets following ROH’s failure to complete its previously agreed repurchase when the hotel lease expired on July 14, 2026.
- ROH reaffirmed on August 14 that it considered itself ready and entitled to repurchase the assets and said it had financial support from an investment backer.
Bangkok’s hotel investment market is heading toward one of its most closely watched property decisions of the year after Orchid Hospitality Co., Ltd., a company controlled by veteran real estate investor Suchad Chiaranussati, submitted a 5.3 billion baht offer to acquire the Royal Orchid Sheraton Hotel and Towers. The riverside property is among Bangkok’s best-known large hotels, and the proposed transaction has placed its future in the hands of unitholders of the Grande Royal Orchid Hospitality Real Estate Investment Trust with Buy-Back Condition, or GROREIT.
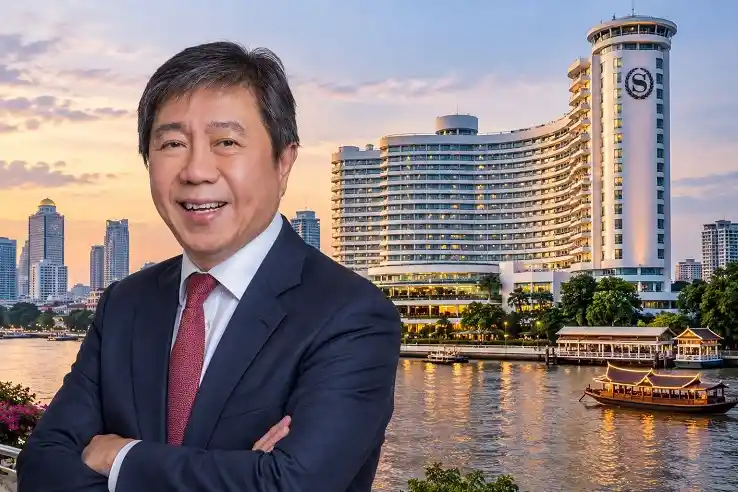
Image Credit: Thailand Hotel News (AI-Generated)
The 5.3 billion baht proposal provides unitholders with an alternative to a 4.873 billion baht repurchase proposal from Royal Orchid Hotel (Thailand) Public Company Limited, or ROH, the property’s former lessee. The difference between the two offers is 427 million baht, adding a significant financial dimension to the decision. At the center of this Thailand Hotel News report is a wider question over how GROREIT should dispose of its principal assets following ROH’s failure to complete its previously agreed repurchase when the hotel lease expired on July 14, 2026. Unitholders are scheduled to consider the options at an electronic meeting on October 28.
Orchid Hospitality Emerges with Higher 5.3 Billion Baht Offer
Orchid Hospitality submitted its written offer on September 4, proposing to acquire the immovable and movable assets associated with the Royal Orchid Sheraton Hotel and Towers project for 5.3 billion baht.
The company is a relatively new entrant in Thailand’s corporate landscape, having been registered on July 8, 2026. Suchad Chiaranussati holds a 99.99 percent stake, placing the prominent real estate investor firmly behind the acquisition proposal.
The bid is particularly notable because of Suchad’s long involvement in Asia-Pacific real estate and hospitality investment. He founded Singapore-headquartered SC Capital Partners in 2004 and serves as its chairman. The investment firm has developed a substantial regional real estate business, including hospitality investments through its Real Estate Capital Asia Partners, or RECAP, fund series.
Suchad’s wider hospitality interests extend across several Asian markets. His investments have included Hotel Management Japan, regional hotel operator Topotels Hotels & Resorts and, more recently, Vietnam-based Fusion Hotel Group. His activities have also extended beyond hotels into residential, commercial and other opportunistic real estate investments across Asia-Pacific.
That background makes the Royal Orchid Sheraton proposal more than simply a bid from a newly incorporated Thai company. Orchid Hospitality may be new, but the investor behind it brings more than two decades of experience in regional real estate investment.
Unitholders Face Three Routes for Hotel Sale
The proposed disposal process follows ROH’s failure to complete the agreed repurchase of the hotel assets when its lease ended on July 14. The missed deadline was subsequently disclosed to the Stock Exchange of Thailand.
One Asset Management Limited, or ONEAM, the trust manager, has called an electronic unitholder meeting for 2 p.m. on October 28, 2026. Unitholders will be asked to consider three possible routes for disposing of the hotel before addressing a proposal to dissolve and liquidate GROREIT.
The first option remains a sale to ROH for 4.873 billion baht. ROH reaffirmed on August 14 that it considered itself ready and entitled to repurchase the assets and said it had financial support from an investment backer.
However, that financial support remains subject to conditions, including due diligence, internal approvals and completion of the necessary documentation. If unitholders approve the ROH proposal, completion would be required within 14 days.
Although the trust manager and trustee maintain that ROH’s contractual repurchase right has expired, the proposal is still being presented to unitholders so that they can evaluate the available options.
Orchid Hospitality Positioned as Alternative Buyer
The second option is the 5.3 billion baht sale to Orchid Hospitality. Its higher price immediately makes it commercially significant, but the sequence of the meeting means ROH’s proposal will be considered first.
Orchid Hospitality’s offer effectively becomes an alternative if unitholders reject the ROH transaction or approve it but ROH subsequently fails to satisfy the required conditions and deadline.
If the Orchid Hospitality transaction proceeds, completion would generally be required within 14 days of unitholder approval. If ROH is initially given approval but later fails to complete its transaction, the timetable for Orchid Hospitality would instead run from the failure of the ROH proposal under the conditions established for the disposal.
The structure gives GROREIT a second identified buyer rather than forcing the trust immediately into an auction should the original repurchase arrangement fail again.
Open Auction Remains the Final Disposal Option
A third route would allow ONEAM to dispose of GROREIT’s principal assets through an open auction. This mechanism would come into play if either or both of the first two proposals are rejected or approved but ultimately cannot be completed.
Under this option, unitholders would provide the trust manager with a general mandate to conduct the auction in accordance with their resolution.
Detailed terms and conditions covering the disposal proposals are expected to be included in the formal meeting notice, which is to be distributed to eligible unitholders at least 14 days before the October meeting.
September 29, 2026, has been set as the record date for determining which GROREIT unitholders are entitled to attend and vote.
Sale Could Lead to Dissolution of GROREIT
The future of the hotel is closely connected to the future of the investment trust itself. A fourth agenda item calls for unitholders to consider dissolving and liquidating GROREIT after a successful disposal of its principal assets.
If a transaction is completed under one of the approved sale routes, the trust manager would move ahead with winding up the trust in accordance with the trust deed and applicable regulations.
Funds would first be reserved for expenses arising during liquidation. These could include liquidation costs, expenses associated with appointing a liquidator and potential litigation costs before the remaining process is completed.
The October 28 vote therefore represents considerably more than a choice between two prices. Unitholders must weigh ROH’s 4.873 billion baht repurchase proposal, Orchid Hospitality’s higher 5.3 billion baht offer and the possibility of testing the property’s value through an open auction.
For Bangkok’s hotel investment sector, the outcome will also determine the next chapter for a major riverside hospitality asset and could add another prominent property to Suchad Chiaranussati’s expanding regional hotel interests. With 427 million baht separating the two identified offers and an auction still available as a fallback, the decision facing GROREIT unitholders combines price, transaction certainty and timing. The October vote should finally provide greater clarity over the ownership of the Royal Orchid Sheraton Hotel and Towers and the eventual winding-up of the trust.
For more on SC Capital Partners, visit: