Key points
- Thailand’s hotel industry is entering a troubling period as weakening tourism demand, rising operating expenses, and increasingly fierce competition threaten the survival of hundreds of accommodation businesses.
- According to KResearch, 148 hotel and accommodation businesses registered closures during the first nine months of 2026, representing a 42% increase compared with the corresponding period in 2025.
- 4 million international arrivals in 2026, down 4% from 2025 and equivalent to just 79% of Thailand’s pre-pandemic visitor volume in 2019.
Thailand’s hotel industry is entering a troubling period as weakening tourism demand, rising operating expenses, and increasingly fierce competition threaten the survival of hundreds of accommodation businesses. Despite continued growth in overall industry revenue, financial difficulties are spreading among smaller hotel operators, particularly those struggling with low occupancy, mounting debts, and limited cash reserves. New findings from Kasikorn Research Center (KResearch) suggest that the situation could deteriorate further in 2027 unless tourism demand strengthens and operators find ways to improve profitability.
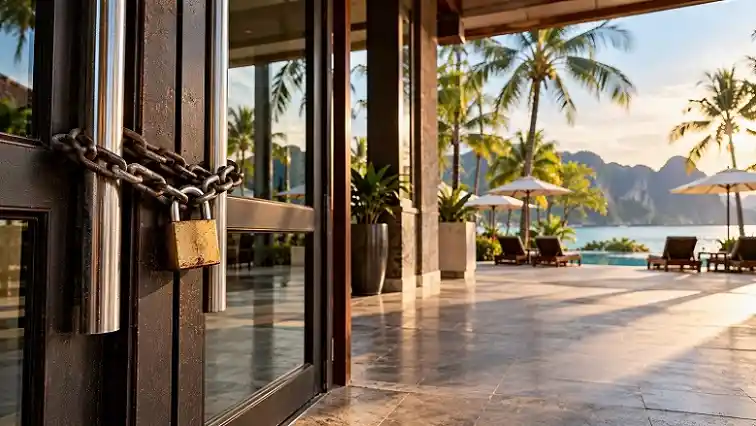
Image Credit: Thailand Hotel News
According to KResearch, 148 hotel and accommodation businesses registered closures during the first nine months of 2026, representing a 42% increase compared with the corresponding period in 2025. The findings highlight a widening gap between Thailand’s tourism ambitions and the financial realities confronting accommodation providers. As this Thailand Hotel News report examines, the industry’s difficulties extend beyond temporary fluctuations in visitor arrivals, reflecting structural problems involving excessive room supply, changing travel preferences, and persistent operating losses. Particularly concerning is that 51% of accommodation operators reported losses in 2025, raising questions about the sustainability of many businesses.
Smaller Hotels Bear the Greatest Financial Burden
Financial pressures are particularly severe among Thailand’s smaller accommodation businesses, which frequently lack the resources and diversified income streams available to major hotel chains.
KResearch found that approximately 54% of small operators recorded losses in 2025. More alarmingly, 42% experienced accumulated losses throughout the three-year period between 2023 and 2025.
Across the entire accommodation industry, approximately 38% of operators suffered accumulated losses during those same three years.
These figures suggest that financial distress is becoming entrenched rather than representing a short-lived downturn. Businesses facing repeated losses may eventually struggle to maintain properties, repay loans, retain employees, or fund necessary renovations.
Industry Revenue Growth Conceals Uneven Recovery
Thailand’s hotel and accommodation market is projected to reach approximately 1.1 trillion baht in 2026, representing growth of 2.6% compared with 2025.
Accommodation services generate roughly 77% of industry revenue, while restaurants, catering, meetings, conferences, and related services contribute the remaining 23%.
The sector comprises approximately 15,000 operators, with small and medium-sized businesses accounting for more than 98%. It also supports around 430,000 jobs and represents approximately 5.7% of Thailand’s gross domestic product at current prices.
However, improving market revenue has not translated into stronger financial performance across the industry.
Nationwide hotel occupancy increased by just 0.18% year on year during the first nine months of 2026, while 19 provinces experienced declining occupancy.
Business formation has also slowed considerably. Only 779 new hotel and accommodation businesses registered during the first nine months, representing a 31.2% annual decline.
International Tourism Remains Below Earlier Expectations
Foreign visitor arrivals continue to present another major challenge.
KResearch forecasts approximately 31.4 million international arrivals in 2026, down 4% from 2025 and equivalent to just 79% of Thailand’s pre-pandemic visitor volume in 2019.
The subdued recovery reflects stronger competition from neighboring destinations, economic uncertainty in important source markets, geopolitical tensions, and concerns surrounding travel safety.
Visitor numbers from 18 significant international markets remained below their 2019 levels during 2025. These included China, Japan, South Korea, Laos, the United States, and several Scandinavian countries.
Tourism patterns are changing as well. Independent travelers increasingly favor cultural experiences, wellness retreats, nature-based activities, and personalized itineraries rather than conventional organized tours.
Such shifts create opportunities for specialized accommodation providers but can disadvantage properties dependent on traditional group bookings.
Domestic tourism has not fully compensated for these weaknesses. In 2025, overnight visitor numbers in 29 provinces remained below pre-pandemic levels, including Bangkok, Phuket, Chiang Mai, and Songkhla.
Expanding Room Supply Intensifies Price Competition
One of the industry’s biggest structural challenges involves accommodation supply expanding faster than overnight tourism demand.
Thailand had approximately 876,000 accommodation rooms during the first half of 2026, an increase of 3.4% compared with the end of 2025 and 11.7% above 2019 levels.
Room inventories expanded across 64 provinces, with major destinations such as Bangkok, Phuket, Chiang Mai, and Surat Thani continuing to attract accommodation investment.
KResearch estimates that average overnight visitors per room declined from 249 in 2019 to 228 in 2026.
This imbalance is forcing some operators to reduce prices to maintain occupancy, potentially sacrificing profitability even when bookings improve.
Competition from alternative accommodation platforms is adding further pressure.
AirDNA figures cited by KResearch identified approximately 50,000 rental units across Bangkok, Phuket, Chonburi, Chiang Mai, and Surat Thani in October 2026.
These units represented roughly 10% of registered accommodation room supply across those markets and recorded average occupancy of approximately 60% over the preceding year.
Against this backdrop, KResearch expects Thailand’s average daily room rate to decline by approximately 0.8% in 2026, following marginal growth of 0.1% in 2025.
Uncertain 2027 Outlook Raises Further Concerns
Looking ahead, KResearch forecasts between 31 million and 33 million international arrivals in 2027, representing potential growth of 5% or a contraction of 1%.
Domestic tourism could generate between 205.5 million and 208 million trips, while nationwide hotel occupancy is projected between 69.58% and 71.69%.
These projections leave little room for financially vulnerable operators to absorb additional shocks.
Variable operating expenses, accounting for approximately 40% to 45% of total costs, could increase through higher electricity charges, transportation expenses, food prices, and online booking commissions.
Geopolitical instability affecting international travel routes could further undermine demand from valuable long-haul markets.
Regulatory Changes and Climate Risks Complicate Recovery
Thailand’s proposed Accommodation Act introduces another consideration for hotel businesses, potentially expanding regulatory oversight across hostels, homestays, boutique properties, and short-term accommodation providers.
Meanwhile, sustainability requirements are becoming increasingly influential among European travelers and corporate customers.
Extreme weather, flooding, higher insurance premiums, and unpredictable booking patterns could create additional financial difficulties.
KResearch recommends diversifying revenue through long-stay packages, cafés, meeting facilities, and co-working services while investing in energy efficiency and technology.
Ultimately, Thailand’s hotel industry faces a difficult adjustment as expanding accommodation capacity collides with slower tourism growth and persistent financial losses. Without stronger demand, disciplined investment, and improved cost management, further closures appear increasingly possible, particularly among smaller independent properties. The coming year could prove decisive for businesses already operating under considerable financial strain.
The KResearch report can be found here:
https://www.kasikornresearch.com/th/analysis/k-social-media/Pages/Hotel-TH-IDP210-FB-2026-10-26.aspx